Can First-Time Buyers Use Washington Down Payment Assistance on a Brand-New Home? (2026 Guide)
By Jon Hodgson, Hodgson Homes - John L. Scott | Last updated November 2026
Short answer: often, yes. Washington's down payment assistance programs, run through the Washington State Housing Finance Commission (WSHFC), are not limited to resale homes. Many first-time buyers use them on new construction. The catch is that builder incentives and state assistance don't always work together, so the order you do things in matters.
This guide walks through how it works, where it gets tricky, and what to do before you visit a sales office.
Quick facts
- Who it's for: First-time and moderate-income buyers looking at brand-new homes near Seattle
- Program: WSHFC down payment assistance, paired with a WSHFC first mortgage through an approved lender
- Required step: A free WSHFC-sponsored homebuyer education class
- Biggest watch-out: Builder incentives tied to the builder's preferred lender
- Related guide: New Construction Homes Near Seattle Under $1 Million (2026 Guide)
How does Washington down payment assistance work?
WSHFC programs help with the upfront cash a purchase takes. The assistance is usually a second loan with deferred or low payments, not a grant, and it's paired with a first mortgage from a WSHFC-approved lender.
To qualify, buyers generally need to:
- Meet income limits for the county (check current)
- Live in the home as their primary residence
- Use a participating lender
- Complete a WSHFC-sponsored homebuyer education class before closing
Assistance amounts, rates and income limits change during the year. Always confirm the current terms with an approved lender or at wshfc.org.
Can I use it on new construction?
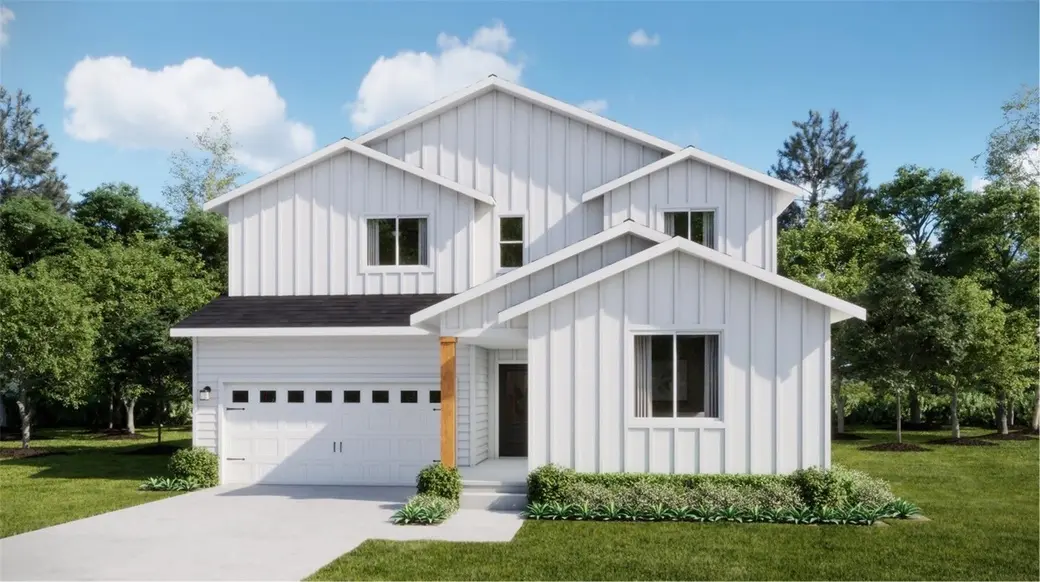
Yes, in many cases. The program looks at you, the loan and the price, not whether the home is new or resale. New builds can work well, because a finished new home usually needs fewer repairs in the first few years.
Where buyers get stuck is the builder incentive.
Why do builder incentives make this tricky?
Most builders offer incentives such as closing-cost credits or a rate buydown, like a 2-1 buydown. These are often available only if you use the builder's preferred lender.
If that lender doesn't offer WSHFC loans, you may have to choose between:
- The builder's incentive, with their lender, or
- State down payment assistance, with a WSHFC-approved lender.
Sometimes the builder will honor part of the incentive with an outside lender. Sometimes their lender is WSHFC-approved and you can have both. You won't know until you ask, and you want to ask before you sign a purchase agreement.
Is new construction a good fit for a first-time buyer?
It can be. Here's what tends to help and what to plan for.
What helps:
- A builder warranty covers many early issues
- Newer systems: heating, water heater, roof and windows
- Energy-efficient construction can mean lower utility bills (ask the builder for estimates)
What to plan for:
- HOA dues: Many new communities have them. Ask what they cover and how often they've gone up.
- Property taxes: Your first tax bill may not reflect the finished home. Ask for an estimate based on the completed value.
- Timing: A home that's still being built can take months. Ask how long the builder will hold your rate lock and what happens if completion slips.
- Extras: Window coverings, fencing, landscaping and upgrades may not be included in the base price.
What should I do before visiting a new-construction sales office?
- Take a free WSHFC homebuyer education class. It's required for the assistance, and it covers the whole process. I co-teach these classes. Ask me for upcoming dates.
- Talk to a WSHFC-approved lender first. Find out what you qualify for and how much assistance may be available (check current).
- Bring your own agent on the first visit. Many builders require your agent to register you at the first visit, or they won't work with your agent later. The builder's sales staff represent the builder.
- Ask how incentives work with outside lenders. Get the answer in writing.
- Compare total monthly cost, not just price. Include HOA dues, estimated taxes, insurance and the rate after any buydown ends.
- Plan your inspections. Even brand-new homes benefit from an independent inspection before drywall goes up (if allowed), a final inspection before closing, and a warranty inspection before the builder's warranty period ends.
Frequently asked questions
Do I have to be a first-time buyer?
Often, but not always. Some WSHFC programs are open to repeat buyers who meet income limits. A WSHFC-approved lender can tell you which programs fit.
Is the homebuyer class really free?
The WSHFC-sponsored homebuyer education classes are free. They cover budgeting, loan options, the buying process and the assistance programs.
Can I combine down payment assistance with a builder's rate buydown?
Sometimes. It depends on whether the builder's incentive is tied to their preferred lender, and whether that lender offers WSHFC loans. Ask both the builder and your lender before you sign.
Where are new homes being built near Seattle?
New construction is spread across King, Snohomish and Pierce counties. See my 2026 guide to new construction near Seattle under $1 million for areas to look at, and my city guides for Renton, Kirkland and Issaquah.
Thinking about a new build?
Jon Hodgson leads Hodgson Homes - John L. Scott in Renton and has been licensed in Washington since 2012. He helps first-time buyers, move-up buyers, downsizers, relocation buyers, investors and developers across Seattle and the Eastside. He also co-teaches free homebuying classes sponsored by the Washington State Housing Finance Commission.
Questions about a new-construction home or the next homebuying class? Call or text (425) 449-0442 or email jonhodgson@johnlscott.com.
Client Focused, Results Driven.
Hodgson Homes - John L. Scott | 4735 NE 4th St Ste 92603, Renton, WA 98059 | WA License #110447. Program details are general information, not loan advice. Confirm current terms with a WSHFC-approved lender.
Categories
Recent Posts